
Your mortgage renewal letter arrives. You open it, look at the new payment and suddenly realize your monthly budget is about to change.
This is called 𝗺𝗼𝗿𝘁𝗴𝗮𝗴𝗲 𝗿𝗲𝗻𝗲𝘄𝗮𝗹 𝘀𝗵𝗼𝗰𝗸.
Many Canadians who received very low mortgage rates a few years ago may now have to renew at a higher rate. Even if your mortgage balance is lower today, the higher interest rate could still increase your payment.
The important question is: 𝗛𝗼𝘄 𝗺𝘂𝗰𝗵 𝗰𝗼𝘂𝗹𝗱 𝘆𝗼𝘂𝗿 𝗽𝗮𝘆𝗺𝗲𝗻𝘁 𝗰𝗵𝗮𝗻𝗴𝗲—and can your household afford it?
How a Higher Rate Changes Your Payment
Your mortgage payment depends mainly on three things:
- Your remaining mortgage balance
- Your new interest rate
- Your remaining amortization
Let’s use a simple example.
Imagine you have a 𝗿𝗲𝗺𝗮𝗶𝗻𝗶𝗻𝗴 𝗺𝗼𝗿𝘁𝗴𝗮𝗴𝗲 𝗯𝗮𝗹𝗮𝗻𝗰𝗲 𝗼𝗳 $𝟱𝟬𝟬,𝟬𝟬𝟬 and 20 years left on your amortization.
Your estimated monthly principal-and-interest payment could be approximately:
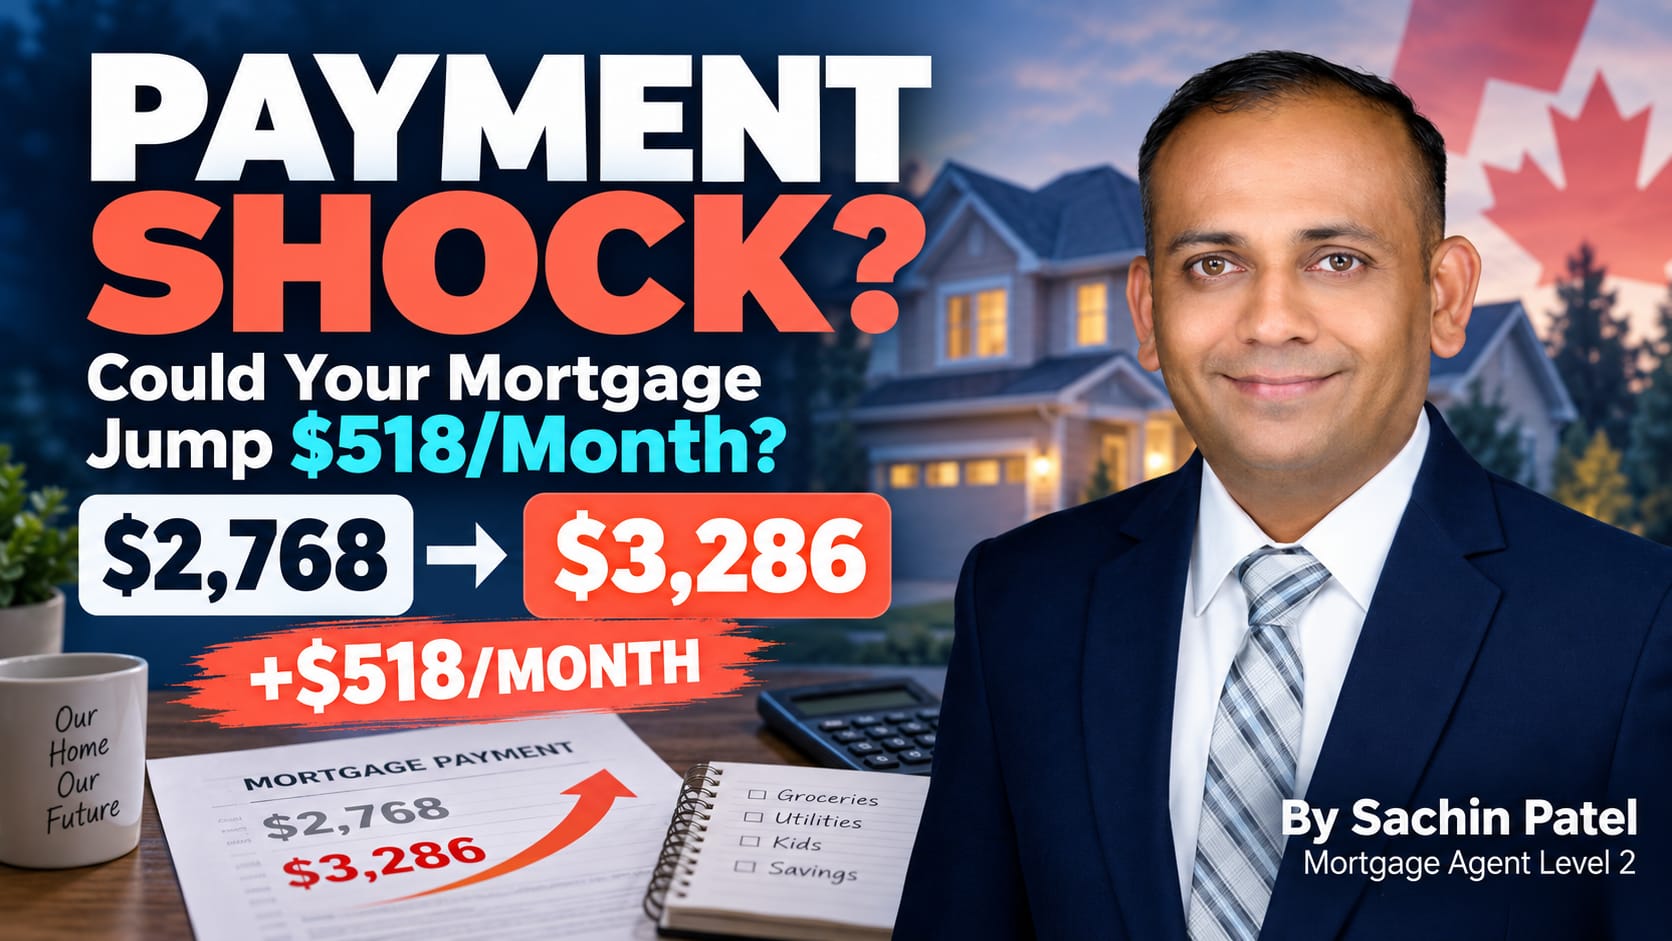
- At 3%: $2,768 per month
- At 4%: $3,021 per month
- At 5%: $3,286 per month
- At 6%: $3,561 per month
Going from 3% to 5% would increase the payment by about 𝗖$𝟱𝟭𝟴 𝗽𝗲𝗿 𝗺𝗼𝗻𝘁𝗵.
That is approximately 𝗖$𝟲,𝟮𝟭𝟲 𝗺𝗼𝗿𝗲 𝗽𝗲𝗿 𝘆𝗲𝗮𝗿.
If the new rate were 6%, the difference from 3% would be about 𝗖$𝟳𝟵𝟯 𝗽𝗲𝗿 𝗺𝗼𝗻𝘁𝗵—or approximately 𝗖$𝟵,𝟱𝟭𝟲 𝗽𝗲𝗿 𝘆𝗲𝗮𝗿.
That is not a small change. It could affect groceries, savings, childcare, travel and other household expenses.
These numbers are estimates for illustration. Your actual payment will depend on your lender, payment schedule and mortgage terms.
What Is a Variable-Rate Mortgage?
Suppose a family currently has $1,000 left each month after paying the mortgage, utilities, groceries, transportation and other regular bills.
If the mortgage payment rises by $518, the family’s extra room falls from $1,000 to only $482.
That smaller amount must now cover:
- Emergency expenses
- Home and car repairs
- Children’s activities
- Clothing and medical costs
- Savings and investments
- Entertainment and travel
A family may technically be able to make the new mortgage payment, but that does not mean the payment is comfortable.
𝗤𝘂𝗮𝗹𝗶𝗳𝘆𝗶𝗻𝗴 𝗳𝗼𝗿 𝗮 𝗺𝗼𝗿𝘁𝗴𝗮𝗴𝗲 𝗮𝗻𝗱 𝗹𝗶𝘃𝗶𝗻𝗴 𝗰𝗼𝗺𝗳𝗼𝗿𝘁𝗮𝗯𝗹𝘆 𝘄𝗶𝘁𝗵 𝘁𝗵𝗲 𝗽𝗮𝘆𝗺𝗲𝗻𝘁 𝗮𝗿𝗲 𝗻𝗼𝘁 𝘁𝗵𝗲 𝘀𝗮𝗺𝗲 𝘁𝗵𝗶𝗻𝗴.
𝗗𝗼𝗻’𝘁 𝗪𝗮𝗶𝘁 𝗳𝗼𝗿 𝘁𝗵𝗲 𝗥𝗲𝗻𝗲𝘄𝗮𝗹 𝗟𝗲𝘁𝘁𝗲𝗿
Start preparing 3 to 4 months before your mortgage renewal date.
Ask your current lender for an early estimate of your new rate and payment. Then compare that offer with other lenders and mortgage products.
Do not look only at the interest rate. Compare:
- The monthly payment
- Fixed versus variable options
- The length of the mortgage term
- Prepayment privileges
- Penalties for ending the new mortgage early
- Fees for switching lenders
- The total interest cost
A lower rate can help, but the mortgage conditions also matter. The wrong mortgage could become expensive if you sell, refinance or make another change before the term ends.
Test the New Payment Before Renewal
Here is a simple way to prepare.
If you expect your payment to rise by $500 per month, begin moving $500 into savings each month before the renewal.
This does two useful things:
𝟭. It shows whether your household can manage the higher payment.
𝟮. It creates extra savings before the new payment begins.
If you cannot manage the test payment, do not ignore the problem. Review your spending and speak with your lender or mortgage professional early.
Your Options If the New Payment Is Too High
Depending on your situation, you may be able to:
- Negotiate a better rate
- Switch to another lender
- Choose a different mortgage term
- Make a lump-sum payment before renewal
- Reduce other high-interest debts
- Change your payment frequency
- Extend the amortization to lower the monthly payment
Extending the amortization may provide short-term relief, but it usually means staying in debt longer and paying more interest. Treat it as a tool—not an automatic solution.
The Bottom Line
Mortgage renewal shock becomes dangerous when it comes as a surprise.
Calculate the possible payment before your renewal. Test the higher amount against your real household budget. Compare lenders and ask questions before signing anything.
A mortgage renewal is not just about getting a new rate. It is about protecting your family’s monthly cash flow.
The earlier you prepare, the more choices you are likely to have.
This article provides general information only. Mortgage rates, payments and qualification requirements vary. Speak with a qualified mortgage professional before making a financial decision.